Global Healthcare Decision Support System Market Size, Share, Trends, Growth 2034
Healthcare Decision Support System Market By Product (Integrated CDSS, and Standalone CDSS), By Delivery Mode (On-Premise, and Cloud-based), By Model (Knowledge-based, and Non-Knowledge based), By Type (Therapeutic, and Diagnostic), By Component (Services, Software, and Hardware), By Application (Advanced CDSS, and Conventional CDSS), By Level of Interactivity (Active CDSS, and Passive CDSS), By Setting (In Patient, and Ambulatory Care Settings), and By Region - Global and Regional Industry Overview, Market Intelligence, Comprehensive Analysis, Historical Data, and Forecasts 2025 - 2034
| Market Size in 2024 | Market Forecast in 2034 | CAGR (in %) | Base Year |
|---|---|---|---|
| USD 2.58 Billion | USD 5.69 Billion | 9.2% | 2024 |
Healthcare Decision Support System Market: Industry Perspective
What will be the global healthcare decision support system market size during the forecast period?
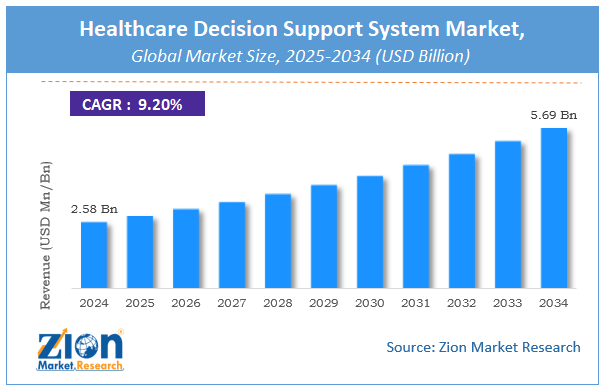
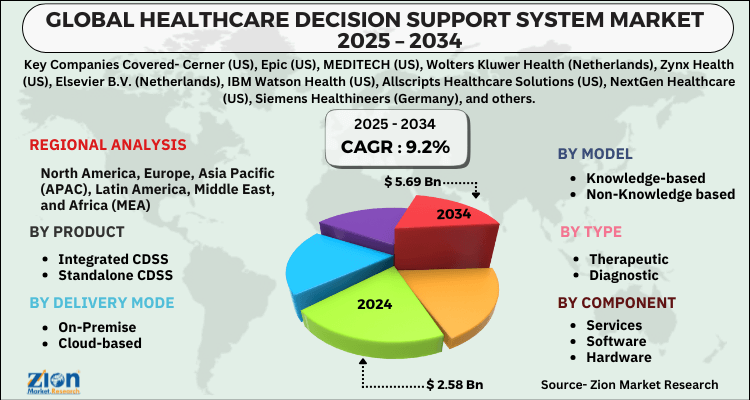
The global healthcare decision support system market size was worth around USD 2.58 billion in 2024 and is predicted to reach around USD 5.69 billion by 2034, with a compound annual growth rate (CAGR) of roughly 9.20% between 2025 and 2034.
This report provides a comprehensive analysis of the growth drivers, restraints, and challenges shaping demand across the global healthcare decision support system market throughout the forecast period, while highlighting high-potential emerging opportunities within the industry.
 Request Free Sample
Key Insights
- As per the analysis shared by our research analyst, the healthcare decision support system market is estimated to grow annually at a CAGR of roughly 9.20% over the forecast period from 2025 to 2034.
- In terms of revenue, the global healthcare decision support system market size was valued at around USD 2.58 billion in 2024 and is projected to reach USD 5.69 billion by 2034.
- The healthcare decision support system market is driven by escalating adoption of electronic health record systems, rising clinical burdens of chronic multi-morbidities, and the urgent imperative to eliminate preventable medical errors through automated, evidence-based alerts.
- Based on the product, the integrated CDSS category accounted for the leading share of 78.4% in the global healthcare decision support system market because embedding clinical intelligence directly into electronic health records delivers seamless point-of-care workflow execution without disrupting clinician routines.
- Based on the delivery mode, the cloud-based category accounted for the leading share of 54.6% in the global healthcare decision support system market because scalable software-as-a-service architectures reduce upfront server outlays, ensure continuous clinical rule updates, and facilitate multi-facility data interoperability.
- Based on the model, the knowledge-based category accounted for the leading share of 82.3% in the global healthcare decision support system market because rule-based reasoning engines grounded in validated medical literature, drug-interaction databases, and clinical practice guidelines provide transparent, legally defensible diagnostic suggestions.
- Based on the type, the therapeutic category accounted for the leading share of 71.5% in the global healthcare decision support system market because automated checking of drug-drug interactions, dosing precision, allergy verifications, and treatment protocol adherence addresses high-risk medical liabilities directly.
- Based on the component, the services category accounted for the leading share of 43.8% in the global healthcare decision support system market because healthcare institutions require extensive consulting, systems integration, customized clinical rule-building, and ongoing user training to achieve successful deployment.
- Based on the application, the conventional CDSS category accounted for the leading share of 62.5% in the global healthcare decision support system market because established computerized provider order entry systems and foundational clinical alert mechanisms remain ubiquitous across global hospital networks.
- Based on the level of interactivity, the active CDSS category accounted for the leading share of 68.2% in the global healthcare decision support system market because proactive real-time notifications and mandatory clinical alerts automatically intercept prescribing errors before orders are finalized.
- Based on the settings, the in patient category accounted for the leading share of 66.7% in the global healthcare decision support system market because high-acuity hospital wards, intensive care units, and emergency departments require continuous, multi-parameter clinical oversight to navigate acute diagnostic complexity.
- North America dominated the global healthcare decision support system market with a revenue share of 46.5% because of comprehensive healthcare IT infrastructure, federal mandates enforcing digital quality measures, high per capita healthcare spending, and substantial presence of leading healthcare technology vendors.
Healthcare Decision Support System Market: Overview
A healthcare decision support system (HDSS) is designed to improve healthcare delivery by merging clinical expertise, patient information, and other health data into medical decisions. Factors such as the increasing global prevalence of chronic diseases and technological advances in big data processing, including machine learning and artificial intelligence (AI) for extracting critical insights, will drive market growth during the forecast period. HDSS has become an important tool in the fight against COVID-19 because it shows how healthcare teams can stay up to date on the latest COVID information and intelligence, improving the quality of care provided.
Rapid advances in biotechnology and bioinformatics are driving improvements and optimizations in data storage, management, and analytics platforms, which will fuel future growth in the HDSS market. With pharmaceutical errors, doctors must make effective and efficient clinical decisions in order to achieve evidence-based clinical outcomes and avoid misdiagnosis during any medical process, fuelling the market's rise in the next years.
Healthcare Decision Support System Market: Driver
What factors are primarily accelerating demand in the healthcare decision support system market?
A medication error is an unintentional failure in the drug treatment process that can harm patients' health. Prescription, dispensing, storage, preparation, and administration errors are the most common preventable causes of unwanted adverse events, posing a significant public health cost. When patients and healthcare providers have access to complete, accurate EHRs that provide a comprehensive patient illness history, they can ensure proper care. Such records can help improve diagnosis, minimize errors, save time, and even shorten patient wait times. To provide quality treatment, hospitals and physicians must deploy and use HDSS and its accompanying technologies, which is boosting adoption worldwide.
Healthcare Decision Support System Market: Restraint
What factors are limiting the expansion of the healthcare decision support system market?
A risk with cloud-based HDSS is that data hosted by the user is not as secure as data stored on-premise. Patient information is sensitive and requires a high level of privacy to ensure only authorized users can access it. The public cloud faces the same security issues as traditional IT systems and is therefore not recommended. Private clouds offer stronger access controls, data security, and systems, but they are not widely used in the healthcare sector because of higher initial costs. Because patient data must be accessed across many departments, major data security risks have arisen. This creates security gaps that hackers can exploit to access critical information. As a result, many hospitals continue to select off-the-shelf solutions over cloud-based solutions, stifling market growth in the coming years.
Healthcare Decision Support System Market: Opportunities
Where do significant growth opportunities lie for the healthcare decision support system market?
Advancements in AI, machine learning, and big data analytics create opportunities to deliver deeper clinical insights and more effective decision support. Integration with existing data handling systems such as EHRs supports predictive scenarios for patients and improved treatment experience.
Growing patient populations, especially in emerging regions, and increased collaboration between healthcare institutions and information technology firms for the development of new systems open additional avenues for market expansion.
Healthcare Decision Support System Market: Challenges
What key challenges confront participants in the healthcare decision support system market?
Ensuring data privacy and security while enabling multi-department access to patient information remains a central challenge. Balancing the benefits of cloud-based flexibility with institutional preferences for on-premise control influences deployment decisions.
Achieving seamless integration with existing clinical workflows and demonstrating clear improvements in outcomes and cost efficiency are ongoing requirements for sustained adoption.
Healthcare Decision Support System Market: Report Scope
| Report Attributes | Report Details |
|---|---|
| Report Name | Healthcare Decision Support System Market |
| Market Size in 2024 | USD 2.58 Billion |
| Market Forecast in 2034 | USD 5.69 Billion |
| Growth Rate | CAGR of 9.2% |
| Number of Pages | 247 |
| Key Companies Covered | Cerner, Epic, MEDITECH, Wolters Kluwer Health, Zynx Health, Elsevier B.V., IBM Watson Health, Allscripts Healthcare Solutions, NextGen Healthcare, Siemens Healthineers, and others. |
| Segments Covered | By Product, By Delivery Mode, By Model, By Type, By Component, By Application, By Level of Interactivity, By Setting, and By Region |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, The Middle East and Africa (MEA) |
| Base Year | 2024 |
| Historical Year | 2020 - 2024 |
| Forecast Year | 2025 to 2034 |
| Customization Scope | Avail customized purchase options to meet your exact research needs. Request For Customization |
Healthcare Decision Support System Market: Segmentation
By product segment, the healthcare decision support system market is divided into integrated CDSS and standalone CDSS. The integrated CDSS category is the dominant division in this sector, commanding substantial market share because it is directly embedded in computerized provider order entry (CPOE) and electronic health record (EHR) environments. Integrating algorithmic decision logic directly into existing clinical software workflows enables medical staff to receive contextual alerts, medication interaction warnings, and diagnostic guidance without switching between disparate applications or re-entering patient vitals. This unified user experience eliminates workflow disruption, accelerates documentation velocity, and maximizes clinician adherence to evidence-based recommendations, solidifying its place as the primary choice for enterprise hospital systems globally. The standalone CDSS category follows as the second most dominant division, maintaining vital commercial presence across specialized medical centers that require deep, highly focused reference databases for complex medical sub-specialties, specialized oncology dosing, or rare disease differential diagnoses without requiring extensive core EHR alterations.
By delivery mode segment, the healthcare decision support system market is divided into on-premise and cloud-based. The cloud-based category represents the most dominant division, capturing high market volume driven by the global transition toward scalable, flexible, and cost-effective health informatics architectures. Cloud-hosted software-as-a-service frameworks significantly diminish heavy initial hardware capital expenditure, automate continuous clinical guideline and pharmacological database updates, and facilitate seamless data interchange across distributed clinical networks and telemedicine platforms. Its exceptional scalability allows healthcare organizations of all sizes to rapidly deploy decision support intelligence without maintaining expansive internal IT engineering teams. The on-premise category stands as the second most dominant division, preserving high commercial value across large academic medical complexes and public healthcare institutions that enforce stringent internal data sovereignty protocols, requiring on-site server storage to maintain exclusive direct custody over confidential patient records.
By model segment, the healthcare decision support system market is divided into knowledge-based and non-knowledge based. The knowledge-based category represents the most dominant division, accounting for the primary market revenue driven by its logical reliance on established clinical rules, expert consensus statements, and verified medical literature. Operating via explicit if-then inference engines that cross-reference patient symptoms and lab results against standardized clinical practice guidelines, knowledge-based models offer transparent, interpretable, and legally defensible recommendations that clinicians readily understand and trust during high-stakes patient encounters. The non-knowledge based category represents the second most dominant division, experiencing rapid technological momentum as healthcare providers increasingly adopt advanced artificial intelligence, neural networks, and pattern-recognition algorithms capable of analyzing complex multi-modal patient data without relying exclusively on pre-programmed expert rules.
By type segment, the healthcare decision support system market is divided into therapeutic and diagnostic. The therapeutic category represents the most dominant division, commanding the leading share of market consumption due to its widespread deployment in managing high-volume, high-liability medical interventions. Therapeutic decision support platforms continuously oversee medication ordering, flagging potentially catastrophic drug-drug interactions, identifying known patient allergies, calculating precise weight-adjusted dosages, and reminding clinicians of required laboratory monitoring for complex pharmaceutical regimens. By serving as an active digital barrier against severe adverse drug events, therapeutic systems protect hospital networks from substantial malpractice exposure and optimize patient clinical outcomes. The diagnostic category stands as the second most dominant division, expanding robustly as clinicians utilize algorithmic differential diagnosis software and AI-enhanced medical imaging tools to navigate complex multi-symptom presentations and detect rare, life-threatening conditions at early clinical stages.
By component segment, the healthcare decision support system market is divided into services, software, and hardware. The services category represents the most dominant division, generating substantial recurring revenue across the market ecosystem. Implementing enterprise clinical decision support involves complex, multi-stage professional services, encompassing systems architecture customization, legacy database integration, ongoing clinician training, and periodic clinical rule configuration to align with evolving medical protocols. Because healthcare providers require continuous technical support, cybersecurity maintenance, and workflow optimization, professional consulting and support services represent the primary ongoing budgetary allocation. The software category follows as the second most dominant division, maintaining immense value through proprietary diagnostic algorithms, regular clinical rule updates, and core analytical licenses that form the intellectual foundation of clinical intelligence.
By application segment, the healthcare decision support system market is divided into advanced CDSS and conventional CDSS. The conventional CDSS category represents the most dominant division, accounting for the largest global deployment volume across established hospital systems and outpatient clinics. Conventional systems encompass foundational clinical rules, standard electronic medication interaction alerts, basic clinical reminders, and standardized order sets that are universally required by public health certification programs and hospital accreditation agencies. Their widespread presence as standard features within commercial electronic medical record suites cements their leading volume footprint. The advanced CDSS category stands as the second most dominant division, demonstrating rapid market adoption as healthcare networks invest in advanced machine learning platforms, natural language processing for unstructured medical notes, and real-time hemodynamic deterioration alerts tailored for high-risk critical care units.
By level of interactivity segment, the healthcare decision support system market is divided into active CDSS and passive CDSS. The active CDSS category represents the most dominant division within this sector, commanding superior market share because proactive, real-time computerized interventions are far more effective at preventing adverse clinical outcomes than static informational tools. Active systems automatically intercept provider orders, displaying mandatory pop-up notifications, dose-adjustment alerts, or required contraindication acknowledgments directly at the moment of electronic order entry. This automated intervention ensures that clinicians cannot inadvertently bypass life-threatening drug conflicts or severe clinical care gaps. The passive CDSS category is the second-largest division, providing on-demand clinical evidence, digital medical calculators, and reference textbooks that clinicians query when seeking deeper therapeutic background information without interrupting standard electronic workflows.
By setting segment, the healthcare decision support system market is divided into in patient and ambulatory care settings. The in patient category represents the most dominant division, capturing high market revenue driven by the extreme clinical acuity, complex therapeutic regimens, and round-the-clock monitoring requirements inherent to hospital environments. Within intensive care wards, emergency departments, and acute surgical suites, hospitalized patients present multifaceted clinical complications requiring continuous algorithmic evaluation of fluctuating vitals, IV medication titrations, and secondary infection indicators. The urgent need to reduce inpatient mortality, control lengths of stay, and prevent costly readmission penalties makes in patient decision support an indispensable operational baseline for acute care health systems. The ambulatory care settings category is the second most dominant division, expanding rapidly as global healthcare delivery shifts toward outpatient surgical centers, urgent care clinics, and primary care practices focused on preventive screening, chronic illness monitoring, and population health management.
Healthcare Decision Support System Market: Regional Analysis
Why will North America continue to dominate the global market during the projection period?
North America is likely to represent a significant share of the worldwide Healthcare decision support systems market because more healthcare institutions are adopting clinical decision systems. Furthermore, new technologies that link existing data-handling systems, such as EHRs and clinical decision systems, provide predictive scenarios for patients, improving patient experience and treatment. Strong digital infrastructure, regulatory focus on quality and safety, and established vendor presence further support regional leadership. This dominance drives overall market growth by sustaining high adoption rates, encouraging continuous product development, and setting standards for integration and evidence-based decision support that influence global trends and expansion.
Asia Pacific has enormous potential for global Healthcare decision support system growth because of the continuously growing patient population and the rising demand for software to help manage it. Furthermore, increased collaboration between healthcare institutions and information technology firms to develop new systems is likely to drive the expansion of global clinical decision support systems in the Asia Pacific.
Recent Developments
- In 2020, Zynx Health announced that it has significantly expanded and upgraded the publicly available COVID-19 clinical decision support available on its website, zynxhealth.com. The most recent additions to the Zynx Health material include suggestions from groups such as the Infectious Diseases Society of America; it is projected to achieve substantial advancements in the worldwide Centers for Disease Control and Prevention and the World Health Organization.
Healthcare Decision Support System Market: Competitive Landscape
The global healthcare decision support system market is dominated by players:
- Cerner
- Epic
- MEDITECH
- Wolters Kluwer Health
- Zynx Health
- Elsevier B.V.
- IBM Watson Health
- Allscripts Healthcare Solutions
- NextGen Healthcare
- Siemens Healthineers
Segments Covered
The global healthcare decision support system market is dominated by players:
By Product
- Integrated CDSS
- Standalone CDSS
By Delivery Mode
- On-Premise
- Cloud-based
By Model
- Knowledge-based
- Non-knowledge-based
By Type
- Therapeutic
- Diagnostic
By Component
- Services
- Software
- Hardware
By Application
- Advanced CDSS
- Conventional CDSS
By Level of Interactivity
- Active CDSS
- Passive CDSS
By Setting
- In Patient
- Ambulatory care settings
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- France
- The UK
- Spain
- Germany
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia Pacific
- The Middle East & Africa
- Saudi Arabia
- UAE
- Egypt
- Kuwait
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Brazil
- Argentina
- Rest of Latin America
Table Of Content
Methodology
FrequentlyAsked Questions
A Healthcare Decision Support System (HDSS) is a computer-based tool designed to assist healthcare professionals in making clinical decisions by providing evidence-based recommendations, patient-specific data analysis, and alerts for potential risks
The global healthcare decision support system market is expected to grow due to increasing demand for data-driven clinical decisions, advancements in AI and big data analytics, rising healthcare digitalization, and growing focus on improving patient outcomes and reducing medical errors.
According to a study, the global healthcare decision support system market size was worth around USD 2.58 Billion in 2024 and is expected to reach USD 5.69 Billion by 2034.
The global healthcare decision support system market is expected to grow at a CAGR of 9.2% during the forecast period.
North America is expected to dominate the healthcare decision support system market over the forecast period.
Leading players in the global healthcare decision support system market include Cerner, Epic, MEDITECH, Wolters Kluwer Health, Zynx Health, Elsevier B.V., IBM Watson Health, Allscripts Healthcare Solutions, NextGen Healthcare, Siemens Healthineers, among others.
The report explores crucial aspects of the healthcare decision support system market, including a detailed discussion of existing growth factors and restraints, while also examining future growth opportunities and challenges that impact the market.
HappyClients