
Aerospace Forging Market Size, Share, Growth, Opportunities 2034

Aerospace Forging Market By Product Type (Closed Die Forging, Open Die Forging, Ring Forging, Investment Casting Forging), By Material (Aluminum Alloys, Titanium Alloys, Nickel Alloys, Steel Alloys), By Application (Aircraft Engines, Landing Gear, Structural Components, Turbine Components), By End User (Commercial Aviation, Military Aviation, Space and Defense, Maintenance, Repair and Overhaul), and By Region - Global and Regional Industry Overview, Market Intelligence, Comprehensive Analysis, Historical Data, and Forecasts 2026 - 2034
| Market Size in 2025 | Market Forecast in 2034 | CAGR (in %) | Base Year |
|---|---|---|---|
| USD 26.10 Billion | USD 39.40 Billion | 3.99% | 2025 |
Aerospace Forging Industry Perspective:
What will be the size of the aerospace forging market during the forecast period?
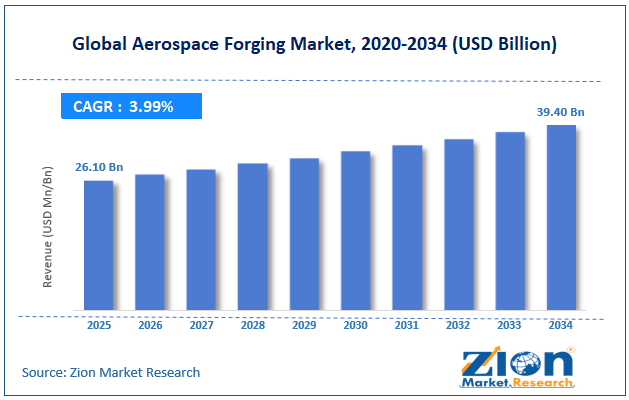
The global aerospace forging market size was valued at approximately USD 26.10 billion in 2025 and is projected to reach around USD 39.40 billion by 2034, growing at a compound annual growth rate of approximately 3.99% between 2026 and 2034.
Key Insights
- As per the analysis shared by our research team, the global aerospace forging market is estimated to grow at a compound annual growth rate of approximately 3.99% during the forecast period from 2026 to 2034.
- In terms of revenue, the global aerospace forging market was valued at approximately USD 26.10 billion in 2025 and is projected to reach USD 39.40 billion by 2034.
- The aerospace forging market is expected to expand steadily, supported by rising aircraft production rates, growing defense budgets, increasing space exploration activity, and continuous upgrades in forging technology.
- Based on product type, closed die forging leads the market because it delivers precise shapes with minimal material waste, while ring forging is gaining strong momentum as engine manufacturers seek seamless components for rotating parts.
- Based on material, titanium alloys lead the market due to their outstanding strength-to-weight ratio and heat resistance. In contrast, nickel alloys are the fastest-growing segment as turbine engines demand materials that perform reliably under extreme heat.
- Based on application, aircraft engines lead the market because each engine requires many forged parts, while structural components are growing steadily as airframe manufacturers focus on weight reduction without compromising strength.
- Based on end user, commercial aviation leads the market due to the continued rise in passenger air travel, while space and defense are growing rapidly as governments and private companies increase investment in space missions and next-generation military aircraft.
- Based on region, North America leads the global aerospace forging market, supported by advanced aerospace manufacturing. At the same time, Asia Pacific is the fastest-growing region, driven by expanding aircraft manufacturing hubs and rising defense spending.
Aerospace Forging Market: Overview
Aerospace forging is a manufacturing process that uses high pressure and heat to shape metal into strong, precise parts for aircraft and spacecraft. This process strengthens the metal’s internal grain structure, allowing forged components to withstand heavy loads, extreme temperatures, pressure, and continuous vibration during flight. The aerospace forging market includes engine components, landing gear, structural parts, turbine sections, and other critical components used in commercial aircraft, military planes, helicopters, and spacecraft. Rising air passenger traffic is encouraging aircraft manufacturers to increase production, creating steady demand for forged aerospace components. Military fleet modernization and higher defense spending are also driving demand for strong, reliable forged parts. Growing investment in satellite launches, space exploration, and new spacecraft is creating additional opportunities for aerospace forging manufacturers. Aircraft and defense companies increasingly require suppliers to provide consistent quality, material traceability, and compliance with strict aviation standards. To meet these requirements, manufacturers are using computer simulation, advanced forging equipment, precision dies, automated production, and inspection systems. The growing use of lightweight aluminum, titanium, and nickel alloys is also helping manufacturers reduce aircraft weight, improve fuel efficiency, increase performance, and lower operating costs.
The aerospace forging industry continues to grow as component manufacturers, aircraft producers, and defense contractors work together to build stronger, lighter, and more reliable parts for the next generation of flight.
Aerospace Forging Market: Strategic Perspective
Where is the aerospace forging market heading?
The aerospace forging market is expected to move toward advanced materials, higher precision, and increased automation across manufacturing facilities. As aircraft manufacturers demand lighter, stronger components, aerospace forgers are investing in improved alloys, automated forging presses, and real-time inspection technologies to reduce defects and support efficient manufacturing of critical aerospace parts.
Where should businesses invest in the aerospace forging market?
The aerospace forging market offers opportunities in titanium and nickel alloy processing, automated inspection equipment, and long-term supply agreements with aircraft and defense manufacturers. Companies investing in energy-efficient furnaces, advanced forging dies, automated production, and skilled metallurgical teams can meet growing demand for complex aerospace components while improving production efficiency and quality control.
What will reshape competition in the aerospace forging market?
Competition in the aerospace forging market will increasingly depend on consistent product quality, strict certification compliance, reliable production capacity, and timely component delivery. Forging companies combining advanced metallurgical expertise with strong traceability, efficient manufacturing systems, and close partnerships with aircraft manufacturers can better meet demanding aerospace requirements while strengthening customer relationships and expanding their market presence.
Aerospace Forging Market: Technology Roadmap 2026–2034
What is the projected development roadmap of the aerospace forging market over the forecast period?
The aerospace forging market is advancing through smarter process controls, wider adoption of advanced lightweight alloys, and growing use of digital simulation before physical production begins, all of which make forged components more reliable and easier to manufacture at scale. The market is expected to grow at a compound annual growth rate of approximately 3.99% over the forecast period, driven by rising aircraft output, evolving defense requirements, and continued refinement of metal-forming technology.
The following roadmap outlines key development phases expected through 2034.
2026–2028: Precision and Efficiency Building Phase
- Simulation-driven design focus: Aerospace forging companies are expected to increase computer modeling to predict metal flow, stress points, and possible design issues before manufacturing the forging dies.
- Defect-reduction technology: Manufacturers are likely to use more advanced ultrasonic and eddy current testing to identify cracks, flaws, and material defects earlier during production.
- Alloy-specific process tuning: Aerospace forgers are expected to adjust temperature and pressure settings for different titanium and nickel alloys to improve quality and consistency across production batches.
2029–2031: Capacity Expansion and Supply Chain Strengthening Phase
- Regional production growth: New aerospace forging facilities are expected to develop near major aircraft manufacturing hubs, helping companies shorten delivery times and reduce transportation costs.
- Material innovation push: Manufacturers are likely to explore advanced alloy combinations and powder metallurgy methods to produce aerospace components with better strength, durability, and fatigue resistance.
- Digital supply chain integration: Real-time tracking tools and shared production data are expected to provide aircraft manufacturers with clearer visibility into forging schedules, material movement, and product quality
2032–2034: Sustainable and Smart Forging Phase
- Green manufacturing adoption: Aerospace forging manufacturers are expected to adopt electric and hybrid furnaces, recycled alloys, and lower-waste production methods as environmental requirements become stricter.
- Predictive maintenance technology: Smart sensors on forging equipment may increasingly detect early signs of wear, helping manufacturers prevent unexpected breakdowns and reduce costly production delays.
- Fully customized component production: Aerospace forging may increasingly support components designed for specific aircraft requirements, with customized shapes and materials developed for individual engines and airframe applications.
Aerospace Forging Market: Dynamics
Growth Drivers
What is driving the rising demand for forged components in the aerospace industry?
The aerospace forging market is growing as commercial aircraft fleets expand, airlines increase routes, and older planes are replaced with newer, fuel-efficient models. Every aircraft requires thousands of forged components, including engine parts, fasteners, landing gear, and structural components, creating consistent demand for aerospace forging manufacturers. Rising defense spending is another major growth driver, as military aircraft, missiles, and defense systems depend on strong forged metal components to perform reliably under demanding conditions. Expanding government and private space programs are also increasing demand for forged components used in rockets and satellites that must withstand extreme launch forces. The shift toward lighter aircraft is encouraging greater use of titanium and aluminum alloys that reduce weight without compromising strength. At the same time, stricter aerospace certification requirements are driving manufacturers to improve testing, documentation, material traceability, and quality control. These factors are encouraging aerospace forging companies to expand production capacity, improve manufacturing precision, and develop stronger, lighter components for aviation, defense, and space applications.
Advanced alloy development is creating opportunities in the aerospace forging market.
The aerospace forging market is being shaped by growing demand for components that offer higher strength, heat resistance, durability, and lower weight. Manufacturers are developing advanced titanium and nickel-based alloys for jet engine components and other aerospace parts exposed to high temperatures and heavy loads. Lightweight forging is becoming increasingly important because reducing aircraft weight can lower fuel consumption, operating costs, and emissions while maintaining structural strength. Manufacturers are also improving forging processes to produce complex components with tighter dimensions and more consistent material properties. Sustainable production is gaining attention through metal scrap recycling, energy-efficient equipment, and processes designed to reduce material waste. Growing demand for advanced propulsion systems, modern aircraft, and high-performance aerospace components is encouraging companies to invest in research, process automation, and improved quality control. These developments are strengthening the capabilities of aerospace forging manufacturers and supporting the production of lighter, stronger, and more durable components across commercial aviation, defense, and space applications.
Restraints
High capital and certification costs are a key challenge limiting growth in the aerospace forging market.
The aerospace forging industry faces financial pressure from high equipment costs, skilled labor, and lengthy certification processes before parts can be approved. Building an aerospace-grade forging facility requires investment in heavy presses, precision dies, furnaces, and testing equipment. Strict aviation certifications require detailed records, regular audits, testing, and quality improvements, increasing operating costs. Smaller forging companies may struggle to afford modern equipment or manage certification expenses, limiting their ability to compete for major contracts. Rising prices for titanium, nickel, and specialty steel alloys can further squeeze profit margins when supply tightens. Manufacturers must also train skilled metallurgists, engineers, and press operators because aerospace forging requires specialized knowledge and process control. Companies can manage these challenges by improving equipment use, simplifying documentation, securing long-term material contracts, and sharing testing facilities through partnerships. These measures can help the aerospace forging market control costs while maintaining safety, quality, and certification requirements.
Opportunities
Will the expansion into commercial space applications open new opportunities in the aerospace forging market?
The aerospace forging market is gaining new opportunities from the rapid expansion of commercial space activities, including rocket launches, satellite deployment, and reusable spacecraft development. Forged components for rocket engines, launch structures, satellite systems, and reusable vehicles require high strength and reliability under extreme temperatures, vibration, and pressure. Aerospace forging manufacturers that can meet these demanding requirements can serve both established aerospace companies and emerging space businesses. The development of electric and hybrid aircraft is creating additional opportunities for specialized forged components used in motor mounts, battery structures, and lightweight support systems. Growing aerospace manufacturing hubs are also creating opportunities as governments encourage domestic production of critical aircraft and defense components. Digital procurement platforms are helping forging companies connect directly with aircraft, defense, and spacecraft manufacturers, expanding access to new contracts. Manufacturers can also benefit from growing demand for forged components used in drones, urban air mobility vehicles, and next-generation defense systems. Sustainable forging, recycled metal use, and long-term supplier partnerships are further creating opportunities across the market.
Challenges
How are raw material shortages and geopolitical factors affecting the aerospace forging market?
The aerospace forging market faces challenges from limited supplies of titanium, nickel, and other specialty metals needed for high-performance components. These materials are produced in only a few regions, making supply vulnerable to mining disruptions, export restrictions, trade changes, and geopolitical tensions. Sudden shortages can increase raw material prices and make production costs harder to manage. Long procurement times for aerospace-grade alloys can also delay manufacturing, especially when aircraft producers need components quickly to maintain assembly schedules. Heavy dependence on a few suppliers can increase the risk of delivery delays and price fluctuations. Limited domestic refining capacity in some countries can further increase reliance on international supply networks. Aerospace forging companies can reduce these risks by working with multiple suppliers, maintaining strategic material inventories, and investing in recycling systems that recover valuable metals from production scrap. Building long-term relationships with mining and refining companies can also improve supply stability. These strategies can help the market manage material shortages, control production costs, maintain schedules, and support reliable component supply despite changing global conditions.
Aerospace Forging Market: Report Scope
| Report Attributes | Report Details |
|---|---|
| Report Name | Aerospace Forging Market |
| Market Size in 2025 | USD 26.10 Billion |
| Market Forecast in 2034 | USD 39.40 Billion |
| Growth Rate | CAGR of 3.99% |
| Number of Pages | 228 |
| Key Companies Covered | Precision Castparts Corp, Howmet Aerospace, Aubert and Duval, VSMPO-AVISMA, Bharat Forge, Doncasters Group, Otto Fuchs, Farinia Group, Sam Yang Precision, Alcoa Corporation, and others. |
| Segments Covered | By Product Type, By Material, By Application, By End User, and By Region |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Base Year | 2025 |
| Historical Year | 2020 - 2024 |
| Forecast Year | 2026 - 2034 |
| Customization Scope | Avail customized purchase options to meet your exact research needs. Request For Customization |
Aerospace Forging Market: Segmentation
The global aerospace forging market is segmented by product type, material, application, end user, and region.
Why does closed die forging lead the aerospace forging market by product type?
Based on product type, the global aerospace forging industry is classified into closed die forging, open die forging, ring forging, and investment casting forging. Closed die forging holds about 46% of the market share, leading because it can produce complex, precise shapes with excellent strength and minimal material waste. Ring forging holds around 21% market share. It is the fastest-growing segment because engine manufacturers increasingly require seamless circular components for rotating turbine and compressor parts.
How is titanium alloy material maintaining its lead in the aerospace forging market?
By material, the aerospace forging market is segmented into aluminum alloys, titanium alloys, nickel alloys, and steel alloys. Titanium alloys account for approximately 38% of the global market share, driven by their exceptional strength-to-weight ratio and resistance to corrosion and heat. Nickel alloys hold around 24% market share. This segment is the fastest-growing, driven by rising demand for components that can withstand the extreme temperatures found inside jet engine hot sections.
Where do aircraft engines stand in the aerospace forging market application landscape?
Based on application, the market is divided into aircraft engines, landing gear, structural components, and turbine components. Aircraft engines lead with about a 41% share because each engine requires many individually forged parts, from turbine blades to compressor discs. Structural components hold around 23% market share. This segment is growing steadily as airframe manufacturers continue prioritizing weight reduction while maintaining structural integrity.
Which end-user accounts for the largest share in the aerospace forging market?
Based on end-user, the market is categorized into commercial aviation, military aviation, space and defense, and maintenance, repair, and overhaul. Commercial aviation accounts for about 47% of the market, leading due to continued growth in global passenger air travel and ongoing fleet expansion by major airlines. Space and defense holds around 22% market share. This segment is expanding quickly as government space agencies and private companies increase the frequency of satellite and rocket launches.
Aerospace Forging Market: Regional Analysis
What factors are strengthening North America's position in the aerospace forging market?
North America leads the global aerospace forging market and is expected to grow at a CAGR of around 5.7% during the forecast period. The region’s strong position is supported by major aircraft manufacturers, a large defense industry, advanced manufacturing facilities, and extensive experience in producing aerospace-grade forged components. The United States and Canada have established forging facilities supplying parts for commercial aircraft, military aircraft, helicopters, engines, and space programs. Government investment in defense modernization, aircraft development, and space exploration is creating steady demand for high-strength forged components. Growing production of fighter aircraft, commercial planes, unmanned systems, and spacecraft is also expanding opportunities for aerospace forging companies. Manufacturers are developing advanced titanium, nickel, aluminum, and steel alloys to meet the requirements of lightweight structures, high-temperature engines, and demanding aerospace applications. Strong research and development capabilities are supporting improvements in forging accuracy, material performance, automation, and quality testing. Efforts to strengthen domestic supply chains are also helping reduce dependence on overseas sources for critical materials and components. Digital manufacturing, advanced inspection systems, and improved process monitoring are further increasing production efficiency and consistency. Growing adoption of advanced forging technologies and lightweight aerospace materials is further strengthening North America’s manufacturing capabilities and supporting long-term regional demand.
How is expanding aircraft manufacturing driving growth in the Asia Pacific aerospace forging market?
The Asia Pacific aerospace forging market is expected to grow at a volume CAGR of around 7.2% during the forecast period, supported by expanding aircraft manufacturing, rising defense spending, and increasing investment in space programs. China, India, Japan, and South Korea are developing stronger aerospace manufacturing capabilities, creating demand for locally produced forged components for aircraft, engines, defense systems, and spacecraft. Governments across the region are also promoting domestic production of critical aerospace parts to reduce import dependence and strengthen local supply chains. International aircraft manufacturers are expanding supplier networks in Asia Pacific to access competitive production costs, skilled workers, and improving technical capabilities. Local forging companies are investing in modern forging equipment, advanced testing systems, and international certifications to qualify for global aerospace programs. Rapid growth in commercial aviation is another major factor, as rising passenger numbers and expanding airline fleets are increasing aircraft production and component requirements. Defense modernization programs are further supporting demand for high-strength forged parts used in military aircraft and other defense platforms. Growing partnerships between regional suppliers and global aerospace companies are also improving technology transfer and manufacturing expertise. Increasing adoption of advanced alloys, automated forging systems, and digital quality inspection is further improving regional production efficiency and component quality.
Recent Market Developments
- In April 2026, Pratt & Whitney, an RTX company, announced a $200 million investment to expand its Columbus Forge facility in Georgia by adding a seventh isothermal forging press. The expansion is expected to increase production of critical compressor and turbine disks by 30% for commercial and military engine programs.
- In March 2026, Aerolloy Technologies, a subsidiary of PTC Industries, completed installation and successful trials of a 4,500/5,100-tonne intelligent open-die forging system in Lucknow, India. The system is designed to process titanium, superalloys, and other advanced materials for aerospace, defense, and space applications.
Aerospace Forging Market: Competitive Analysis
The leading players in the global aerospace forging market are:
- Precision Castparts Corp
- Howmet Aerospace
- Aubert and Duval
- VSMPO-AVISMA
- Bharat Forge
- Doncasters Group
- Otto Fuchs
- Farinia Group
- Sam Yang Precision
- Alcoa Corporation
The global aerospace forging market is segmented as follows:
By Product Type
- Closed Die Forging
- Open Die Forging
- Ring Forging
- Investment Casting Forging
By Material
- Aluminum Alloys
- Titanium Alloys
- Nickel Alloys
- Steel Alloys
By Application
- Aircraft Engines
- Landing Gear
- Structural Components
- Turbine Components
By End User
- Commercial Aviation
- Military Aviation
- Space and Defense
- Maintenance, Repair, and Overhaul
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- France
- The UK
- Spain
- Germany
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia Pacific
- The Middle East & Africa
- Saudi Arabia
- UAE
- Egypt
- Kuwait
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Brazil
- Argentina
- Rest of Latin America
Table Of Content
Methodology
FrequentlyAsked Questions
Aerospace forging is a manufacturing process that uses high pressure and heat to shape metal into strong, precise parts for aircraft and spacecraft. This process strengthens the metal’s internal grain structure, allowing forged components to withstand heavy loads, extreme temperatures, pressure, and continuous vibration during flight.
The global aerospace forging market is expected to grow due to rising aircraft production, increasing defense spending, growing space exploration activity, and continuous advancement in forging technology and alloy development.
According to research, the global aerospace forging market was valued at approximately USD 26.10 billion in 2025 and is projected to reach approximately USD 39.40 billion by 2034.
The compound annual growth rate of the aerospace forging market is expected to be approximately 3.99% from 2026 to 2034.
North America is expected to lead the global aerospace forging market throughout the forecast period, driven by its established aircraft manufacturing base, strong defense industry, and deep metallurgical expertise.
The major players in the global aerospace forging market include Precision Castparts Corp, Howmet Aerospace, Aubert and Duval, VSMPO-AVISMA, Bharat Forge, Doncasters Group, Otto Fuchs, Farinia Group, Sam Yang Precision, and Alcoa Corporation.
The report examines key aspects of the aerospace forging market, including research and development drivers, adoption barriers, application opportunities, competitive landscape dynamics, detailed regional market performance analysis, and a comprehensive forward-looking outlook across all major product types, materials, applications, end-user segments, and geographic regions through 2034.
Technological advancement is making the aerospace forging market more precise and efficient through simulation-driven design, advanced alloy processing, and improved defect-detection systems. These innovations help manufacturers produce lighter, stronger components that improve aircraft fuel efficiency and safety.
Which application areas will offer significant growth opportunities in the aerospace forging market?
Aircraft engines, landing gear systems, and structural airframe components will offer strong opportunities in the aerospace forging market, as manufacturers increasingly seek forged parts that deliver greater strength, reduced weight, and longer service life.
Emerging trends in the aerospace forging market include advanced titanium and nickel alloy development, digital simulation tools, sustainable manufacturing practices, and improved inspection technology, helping manufacturers produce components with greater precision, durability, and reliability.

HappyClients

