Global Industrial Sensors Market Size, Share, And Growth Report 2032
Industrial Sensors Market By Product (Image Sensor, Level Sensor, Pressure Sensor, Gas Sensor, Temperature Sensor, Position Sensor, Force Sensor, Flow Sensor, and Humidity & Moisture Sensor), By Positional Type (Contact and Non-Contact), By End-Use Industry (Oil and Gas, Manufacturing, Water and Wastewater, Pharmaceuticals, Power Generation, Chemicals, Mining, and Others), and By Region - Global And Regional Industry Overview, Market Intelligence, Comprehensive Analysis, Historical Data, And Forecasts 2024-2032
| Market Size in 2023 | Market Forecast in 2032 | CAGR (in %) | Base Year |
|---|---|---|---|
| USD 26.83 Billion | USD 46.49 Billion | 6.3% | 2023 |
Industrial Sensors Industry Perspective
What will be the global industrial sensors market size during the forecast period?
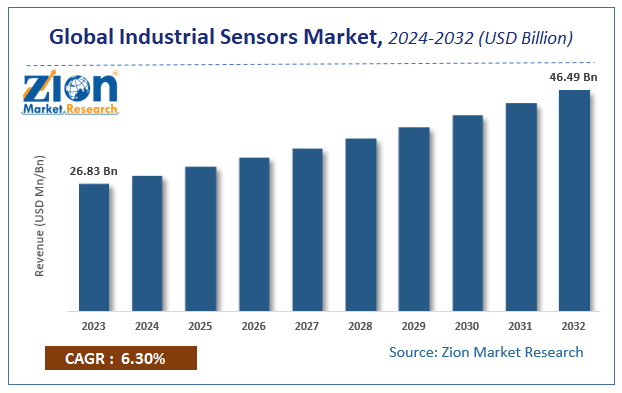
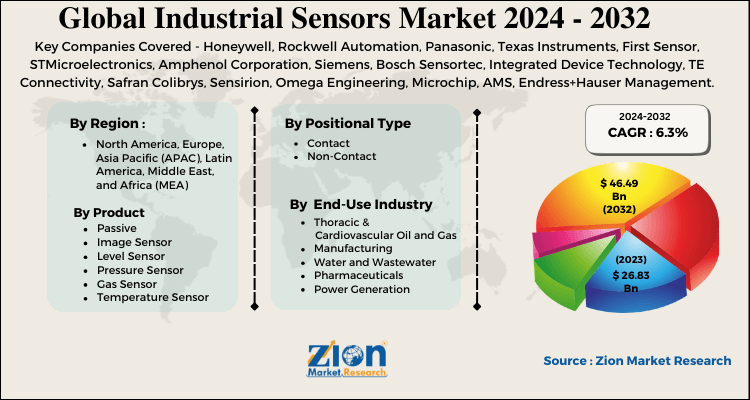
The global industrial sensors market size was worth around USD 26.83 billion in 2023 and is predicted to reach around USD 46.49 billion by 2032, with a compound annual growth rate (CAGR) of roughly 6.3% between 2024 and 2032.
This report provides a comprehensive analysis of the growth drivers, restraints, and challenges shaping demand across the global industrial sensors market throughout the forecast period, while highlighting high-potential emerging opportunities within the industry.
Key Insights
- As per the analysis shared by our research analyst, the global industrial sensors market is estimated to grow annually at a CAGR of around 6.3% over the forecast period (2024-2032).
- In terms of revenue, the global industrial sensors market size was valued at around USD 26.83 billion in 2023 and is projected to reach USD 46.49 billion by 2032.
- The industrial sensors market is projected to grow at a significant rate due to rising demand from Industry 4.0 and IIoT, growing awareness across end-user industries, increasing adoption of wireless sensors, and rising demand for industrial robots.
- Based on the product segment, pressure sensors are anticipated to be the fastest-growing segment owing to their critical role in process monitoring, safety systems, and automation across multiple industries.
- Based on the positional type segment, the non-contact type segment was the fastest-growing and accounted for a significant share in 2023 due to advantages in reliability, reduced wear, and suitability for harsh industrial environments.
- Based on the end-use industry segment, the power generation segment dominated the industrial sensors market globally in 2023, driven by extensive requirements for temperature, pressure, flow, and level monitoring in power plants.
- Based on region, Europe has been leading the industrial sensors market and is anticipated to continue on the dominant position due to stringent regulatory standards and safety directives across the region.
Industrial Sensors Market: Overview
Industrial sensors play a vital role across diverse end-user industries by enabling the analysis, measurement, processing, and detection of a wide range of changes such as length, position, exterior characteristics, height, temperature, pressure, and dislocation occurring within and around industrial manufacturing locations. These devices form the foundational sensing layer that supports process control, quality assurance, predictive maintenance, and operational safety in modern industrial environments.
Industrial Sensors Market: Growth Drivers
What factors are propelling the expansion of the industrial sensors market?
The global industrial sensors market is likely to experience significant growth over the upcoming years, owing to rising demand for industrial sensors by the growing Industrial 4.0 and industrial internet of things (IIoT) and growing awareness of industrial sensor measures among all end-user industries. The increasing use of wireless sensors and rising demand for industrial robots are expected to further propel the industrial sensors market in the upcoming years. Rapid industrialization and execution of industrial sensor measures by numerous governments are also expected to drive the industrial sensors market globally in the years to come.
Industrial Sensors Market: Restraints
What factors are limiting the growth of the industrial sensors market?
However, the huge initial investments for the installation of industrial sensor systems may limit the global industrial sensors market development. Alternatively, the rise in the acceptance of workplace safety standards, especially in emerging countries, is likely to create new growth opportunities for the major market players.
Industrial Sensors Market: Report Scope
| Report Attributes | Report Details |
|---|---|
| Report Name | Industrial Sensors Market |
| Market Size in 2023 | USD 26.83 Billion |
| Market Forecast in 2032 | USD 46.49 Billion |
| Growth Rate | CAGR of 6.3% |
| Number of Pages | 220 |
| Key Companies Covered | Honeywell, Rockwell Automation, Panasonic, Texas Instruments, First Sensor, STMicroelectronics, Amphenol Corporation, Siemens, Bosch Sensortec, Integrated Device Technology, TE Connectivity, Safran Colibri, Sensirion, Omega Engineering, Microchip, AMS, Endress+Hauser Management, NXP Semiconductors, Figaro Engineering, and Teledyne Technologies |
| Segments Covered | By Product, By Positional Type, By End-Use Industry, and By Region |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Base Year | 2023 |
| Historical Year | 2018 - 2022 |
| Forecast Year | 2024 - 2032 |
| Customization Scope | Avail customized purchase options to meet your exact research needs. Request For Customization |
Industrial Sensors Market: Segmentation
The industrial sensors market is segmented by product, positional type, end-use industry, and region. All the segments of the industrial sensors market have been analyzed based on present and future trends, and the market is estimated from 2024 to 2032.
Based on Product Segment, the industrial sensors market is categorized into image sensor, level sensor, pressure sensor, gas sensor, temperature sensor, position sensor, force sensor, flow sensor, and humidity and moisture sensor. Pressure sensors are anticipated to be the fastest-growing segment in the industrial sensors market in the future. Their critical importance in monitoring process parameters, ensuring equipment safety, and supporting automation across oil and gas, manufacturing, power generation, and chemical industries underpins strong demand. Continuous innovation in accuracy, durability, and digital output capabilities further strengthens their market position. This growth helps drive overall market expansion by addressing essential needs for real-time pressure data in both critical and general industrial applications, encouraging broader sensor adoption and system upgrades.
Based on positional type segment, the market for industrial sensors includes contact and non-contact types. The non-contact type segment was the fastest-growing in the global market and accounted for a significant share in 2023. Non-contact sensors offer advantages including reduced mechanical wear, longer service life, and the ability to operate effectively in harsh or contaminated environments without physical interaction with the target. These characteristics make them highly suitable for continuous monitoring applications in manufacturing, power generation, and process industries. Their dominance and rapid growth help drive market development by supporting higher reliability standards and enabling sensor deployment in previously challenging locations, thereby expanding overall addressable applications.
Based on End-Use Industry Segment, the industrial sensors market comprises oil and gas, manufacturing, water and wastewater, pharmaceuticals, power generation, chemicals, mining, and others. In 2023, the power generation segment dominated the industrial sensors market globally. This leadership position drives overall market growth by generating substantial volume requirements and encouraging ongoing investment in advanced sensing technologies that improve plant efficiency and safety.
Industrial Sensors Market: Regional Analysis
Why will Europe continue to dominate the global market during the projection period?
Europe has been leading the industrial sensors market and is anticipated to continue in a dominant position in the years to come. The region benefits from stringent regulatory standards and safety directives that mandate comprehensive monitoring and control systems across industrial facilities. Strong manufacturing bases in countries such as Germany, the United Kingdom, France, and Italy, combined with advanced Industry 4.0 initiatives and high adoption of automation technologies, support sustained demand. Continuous investment in research, innovation, and smart factory development further reinforces Europe’s leadership and drives overall market growth, technological advancement, and expansion of high-performance sensor solutions.
Asia Pacific is anticipated to be the fastest-growing region over the next few years. Swift urbanization and rapid industrialization across the region, particularly in China, India, Japan, and South Korea, are accelerating the deployment of industrial sensors. Expanding manufacturing capacity, government support for automation, and rising investments in infrastructure and energy projects contribute to robust growth momentum and increasing contribution to the global market.
Recent Developments
- In January 2026, Teledyne Technologies acquired DD-Scientific to expand its electrochemical gas sensor portfolio for industrial safety applications in power generation, petrochemicals, and semiconductors.
- In October 2025, STMicroelectronics launched four 5MP CMOS image sensors under the ST BrightSense line featuring dual global/rolling shutter, on-chip RGB-IR separation, and high-speed capture for industrial automation, robotic vision, and related applications.
- In September 2025, Honeywell introduced its new 13MM Pressure Sensor designed specifically for cleanroom environments critical to semiconductor manufacturing.
Industrial Sensors Market: Competitive Players
Some major players in the global industrial sensors market are:
- Honeywell
- Rockwell Automation
- Panasonic
- Texas Instruments
- First Sensor
- STMicroelectronics
- Amphenol Corporation
- Siemens
- Bosch Sensortec
- Integrated Device Technology
- TE Connectivity
- Safran Colibriys
- Sensirion
- Omega Engineering
- Microchip
- AMS
- Endress+Hauser Management
- NXP Semiconductors
- Figaro Engineering
- Teledyne Technologies
Industrial Sensors Market: Key Trends
Increasing integration of wireless and IIoT-enabled sensors
The shift toward wireless sensor networks and IIoT platforms is enabling more flexible, scalable, and cost-effective monitoring solutions. These systems support real-time data collection, remote diagnostics, and predictive analytics, reducing installation complexity and expanding deployment possibilities across industrial facilities.
Rising demand for smart sensors supporting Industry 4.0 and predictive maintenance
Advanced sensors with embedded intelligence, digital outputs, and diagnostic capabilities are gaining traction as manufacturers prioritize predictive maintenance, process optimization, and energy efficiency. This trend is driving innovation in sensor accuracy, connectivity, and integration with higher-level control and analytics systems.
The global industrial sensors market is segmented as follows
By Product
- Image Sensor
- Level Sensor
- Pressure Sensor
- Gas Sensor
- Temperature Sensor
- Position Sensor
- Force Sensor
- Flow Sensor
- Humidity and Moisture Sensor
By Positional Type
- Contact
- Non-Contact
By End-Use Industry
- Oil and Gas
- Manufacturing
- Water and Wastewater
- Pharmaceuticals
- Power Generation
- Chemicals
- Mining
- Others
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- France
- The UK
- Spain
- Germany
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia Pacific
- The Middle East & Africa
- Saudi Arabia
- UAE
- Egypt
- Kuwait
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Brazil
- Argentina
- Rest of Latin America
Table Of Content
Methodology
FrequentlyAsked Questions
Industrial sensors play a vital role in various end-user industries, as aid one to analyze, measure, process, and detect a wide range of changes, such as length, position, exterior, height, temperature, pressure, and dislocation, happening in and around the industrial manufacturing locations.
According to study, the Industrial Sensors Market size was worth around USD 26.83 billion in 2023 and is predicted to grow to around USD 46.49 billion by 2032.
The CAGR value of Industrial Sensors Market is expected to be around 6.3% during 2024-2032.
Europe has been leading the Industrial Sensors Market and is anticipated to continue on the dominant position in the years to come.
The Industrial Sensors Market is led by players like Honeywell, Rockwell Automation, Panasonic, Texas Instruments, First Sensor, STMicroelectronics, Amphenol Corporation, Siemens, Bosch Sensortec, Integrated Device Technology, TE Connectivity, Safran Colibrys, Sensirion, Omega Engineering, Microchip, AMS, Endress+Hauser Management, NXP Semiconductors, Figaro Engineering, and Teledyne Technologies.
Key growth drivers include rising demand from Industry 4.0 and the Industrial Internet of Things (IIoT), growing awareness of sensor applications across end-user industries, increasing use of wireless sensors, rising demand for industrial robots, rapid industrialization, and government initiatives supporting sensor deployment.
The report explores crucial aspects of the industrial sensors market, including a detailed discussion of existing growth factors and restraints, while also examining future growth opportunities and challenges that impact the market. It provides comprehensive analysis of segmentation by product, positional type, and end-use industry, regional dynamics, competitive landscape, and historical and forecast data.
HappyClients