Global Soy Sauce Market Size, Share, Trends, Growth and Forecast 2032
Soy Sauce Market: By Application (Food Industry and Household), By Type (Blended and Brewed), and By Region - Global Industry Perspective, Comprehensive Analysis, and Forecast, 2024 - 2032
| Market Size in 2023 | Market Forecast in 2032 | CAGR (in %) | Base Year |
|---|---|---|---|
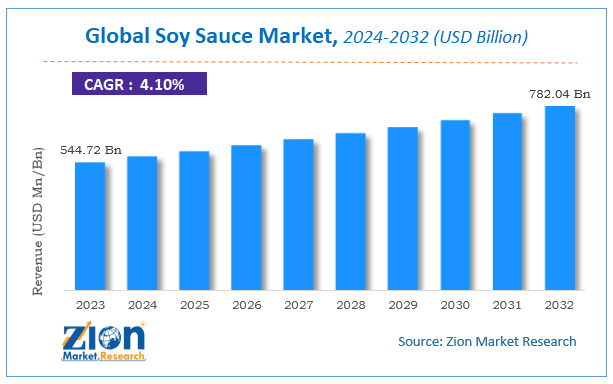
| USD 544.72 Billion | USD 782.04 Billion | 4.1% | 2023 |
What is the Soy Sauce Market Size?
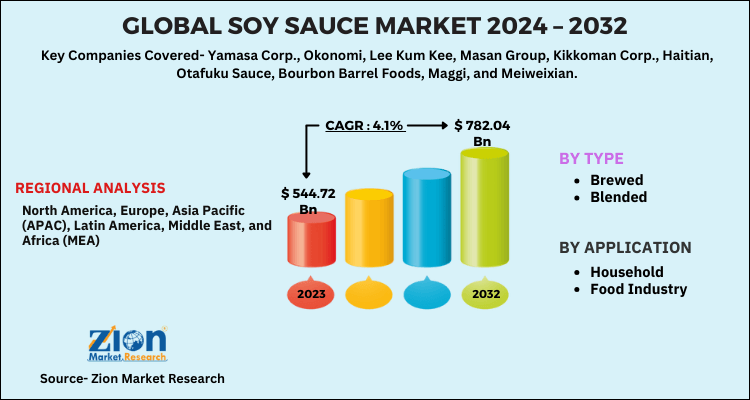
According to Zion Market Research, the global Soy Sauce Market was worth USD 544.72 Billion in 2023. The market is forecast to reach USD 782.04 Billion by 2032, growing at a compound annual growth rate (CAGR) of 4.1% during the forecast period 2024-2032. The report offers a comprehensive analysis of the market, highlighting the factors that will determine growth, potential challenges, and opportunities that could emerge in the Soy Sauce industry over the next decade.
Sauce Market Overview
Soy sauce is a popular condiment that has been widely used in Asian cuisine for centuries. It is a dark, salty liquid made from fermented soybeans, wheat, salt, and water, with variations in ingredients and preparation methods across different regions and cultures. Soy sauce is commonly used as a seasoning in dishes such as stir-fries, marinades, and dipping sauces, and it is also used as a table condiment. The growth of the global soy sauce market is driven by various factors, including the increasing popularity of Asian cuisine and the growing demand for natural and healthy food products. Soy sauce is considered to be a healthy alternative to other condiments, such as ketchup and mayonnaise, as it is lower in calories, fat, and sugar, and contains beneficial nutrients like protein and amino acids.
The increasing preference for soy sauce as a seasoning component and flavor additive is the primary driver of the global soy sauce market. During the forecast period, food retail chains, manufacturers, and restaurants are projected to influence the market. Soy sauce is becoming a popular ingredient in a variety of popular cuisines, including Chinese, Japanese, Indonesian, Thai, Malaysian, and Vietnamese. A growing variety of country cuisines utilizing the market as their primary component will accelerate market expansion significantly during the forecast period on a global scale.
Soy Sauce Market Introduction
Soy sauce is a traditional fermented all-purpose seasoning which is most popular in East Asia and is exported from the East Asian countries to other parts across the globe. It has a salt taste as well as sharp flavor. Furthermore, in the traditional process of soy sauce preparation, roasted wheat & cooked soybeans are added to aspergillus species spores. Then the mixture is fermented for span of two days in order to produce koji, which is then added to brine for producing moromi, a kind of mash that ferments resulting in soy sauce production. Additionally, phenolic compounds including 4-ethylphenol and 4-ethylguaiacol are added to soy sauce to impart flavor to it.
Furthermore, it takes more than six months for complete fermentation and moromi mash aging. Thus, soy sauce production through traditional methods is a time-consuming process and hence new methods for its continuous brewing or fermentation are utilized.
In Japan, soy sauce is referred as shoyu is prepared from wheat and soybeans mixed in the equal proportion. The two raw constituents are broken down into peptides and amino acids with the help of microbial proteolytic enzymes after fermentation.
Soy Sauce Market Growth Dynamics
As per NCBI study, the soy sauce (shoyu) comprises of nearly 1% of shoyu polysaccharides that demonstrate anti-allergic features in vivo and in vitro. Moreover, oral shoyu polysaccharides supplements have proved to be effective against allergic rhinitis. Thus, soy sauce has proved as a promising seasoning for treating allergic ailments through diet due to its anti-allergic as well as hypoallergenic characteristics. All these aforementioned aspects are anticipated to steer the growth of soy sauce market over the coming years.
According to NCBI, research conducted in year 2005 on shoyu to study its functional effects demonstrated favorable or beneficial outcomes on human health. For instance, the intake of soup consisting of soy sauce increased the gastric juice secretion in humans, thereby improving & catalyzing the digestive process in humans.
Furthermore, soy sauce exhibits antimicrobial features against bacteria including Staphylococcus aureus, Vibrio cholera, nonpathogenic Escherichia coli, Salmonella enteritidis, Shigella flexneri, and pathogenic E. coli. Apart from this, the product also comprises of anti-hypertensive constituents and displays anti-carcinogenic effects. All these factors are likely to lucratively influence the expansion of soy sauce industry over the forecasting years.
Soy Sauce Market: Report Scope
| Report Attributes | Report Details |
|---|---|
| Report Name | Soy Sauce Market |
| Market Size in 2023 | USD 544.72 Billion |
| Market Forecast in 2032 | USD 782.04 Billion |
| Growth Rate | CAGR of 4.1% |
| Number of Pages | 110 |
| Key Companies Covered | Yamasa Corp., Okonomi, Lee Kum Kee, Masan Group, Kikkoman Corp., Haitian, Otafuku Sauce, Bourbon Barrel Foods, Maggi, and Meiweixian |
| Segments Covered | By Type, By Application And By Region |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Base Year | 2023 |
| Historical Year | 2018 - 2022 |
| Forecast Year | 2024 - 2032 |
| Customization Scope | Avail customized purchase options to meet your exact research needs. Request For Customization |
Soy Sauce Market Segmentation
The Orthopedic Implants market is segmented by product type, biomaterial, type, and region.
Based on Product Type Segment, The Orthopedic Implants market is divided into Reconstructive Joint Replacements, Spinal Implants, Dental Implants, Trauma, Orthobiologics, and others. Reconstructive Joint Replacements represent the most dominant sub-segment, driven by the rising prevalence of osteoarthritis and osteoporosis, continuous technological advancements in knee and hip replacement systems, and elevated research and development investments by leading manufacturers. These implants restore mobility and significantly improve patient quality of life, generating high procedural volumes that propel overall market growth. Spinal Implants rank as the second most significant category, supported by increasing incidence of degenerative disc disease and trauma-related spinal injuries, with fusion devices and motion-preservation technologies contributing substantially to revenue and clinical innovation.
Based on Biomaterial Segment, The Orthopedic Implants market is divided into Metallic Biomaterials, Polymeric Biomaterials, Ceramic Biomaterials, and others. Metallic Biomaterials hold the leading position due to their superior mechanical strength, fatigue resistance, corrosion resistance, and long-established clinical track record in load-bearing applications such as joint replacements and trauma fixation devices. Titanium alloys, stainless steel, and cobalt alloys provide reliable performance under high stress, supporting widespread adoption and driving market volume. Ceramic Biomaterials form the second major category, valued for excellent biocompatibility, wear resistance, and aesthetic properties that make them suitable for certain joint articulating surfaces and dental applications, thereby expanding material options and supporting specialized growth.
Based on Type Segment,
The Orthopedic Implants market is divided into Knee, Hip, Wrist & Shoulder, Dental, Spine, Ankle, and others. Knee implants dominate the segment because of the high incidence of knee osteoarthritis among the aging population and the proven success of total and partial knee replacement procedures in restoring function and reducing pain. These procedures account for a large share of reconstructive surgeries and continue to drive market expansion through technological refinements. Hip implants constitute the second most dominant type, benefiting from similar demographic trends and strong clinical outcomes in total hip arthroplasty, which further reinforces overall demand for reconstructive orthopedic solutions.
Regional Analysis
Why will North America continue to dominate the global market during the projection period?
North America is projected to maintain its leading position throughout the forecast period. Growth is underpinned by a rising aging population affected by osteoarthritis and osteoporosis, which drives high volumes of joint replacement and fracture fixation procedures. Increasing sports-related injuries further elevate demand for trauma and reconstructive implants. The region benefits from advanced healthcare infrastructure, high healthcare expenditure, well-established reimbursement frameworks, and the presence of major industry players that continuously introduce innovative technologies. These factors collectively sustain North America’s influence on global market trends, clinical standards, and capacity expansion.
Europe holds a strong secondary position supported by sophisticated healthcare systems and significant elderly populations in countries such as Germany, the United Kingdom, France, and Italy. Emphasis on high-quality care, early adoption of advanced implants, and ongoing research into minimally invasive techniques contribute to steady regional growth and technological leadership.
Asia Pacific is expected to record robust expansion driven by improving healthcare infrastructure, rising disposable incomes, growing awareness of orthopedic treatments, and a large aging demographic in China, Japan, India, and South Korea. Increasing investments in medical facilities and expanding access to specialized surgical care accelerate adoption of both reconstructive and trauma implants.
Latin America and the Middle East & Africa represent emerging opportunities. Gradual modernization of healthcare systems, rising incidence of trauma and degenerative conditions, and expanding private healthcare sectors support progressive market development, although overall penetration remains lower than in more mature regions.
Recent Developments
- In early 2026, Zimmer Biomet completed its acquisition of Paragon 28, a foot and ankle specialist, and subsequently launched two new devices including the Gorilla Pilon Fusion Plating System and the Phantom TTC Trauma Nail to expand its extremities and trauma portfolio.
- In September 2026, Stryker agreed to acquire ZuriMED, developer of the FiberLocker system for rotator cuff augmentation, strengthening its sports medicine and shoulder care offerings.
- In June 2026, Zimmer Biomet entered into an agreement to acquire Pacira Biosciences’ iovera cryoneurolysis device business for pain management applications relevant to orthopedic procedures.
- In July 2025, Zimmer Biomet announced the acquisition of orthopedic robotics maker Monogram Technologies to enhance its robotic-assisted surgery capabilities.
Key players profiled in the report include
- Yamasa Corp.
- Okonomi
- Lee Kum Kee
- Masan Group
- Kikkoman Corp.
- Haitian
- Otafuku Sauce
- Bourbon Barrel Foods
- Maggi
- Meiweixian.
The global soy sauce market is segmented as follows:
By Type
- Brewed
- Blended
By Application
- Household
- Food Industry
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- France
- The UK
- Spain
- Germany
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia Pacific
- The Middle East & Africa
- Saudi Arabia
- UAE
- Egypt
- Kuwait
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Brazil
- Argentina
- Rest of Latin America
Table Of Content
Methodology
FrequentlyAsked Questions
Soy sauce is a fermented liquid seasoning made from soybeans. It adds salty and umami flavor to food
The global Soy Sauce market is expected to be driven by the rising global consumption of Asian cuisines and demand for fermented condiments. Expansion of foodservice and retail channels supports growth.
According to study, the global Soy Sauce market size was worth around USD 544.72 Billion in 2023 and is predicted to grow to around USD 782.04 Billion By 2032.
The global Soy Sauce market is expected to grow at a Compound Annual Growth Rate (CAGR) of around CAGR 4.1% during the forecast period from 2024-2032.
The global Soy Sauce industry is projected to be challenged by Challenges include sodium-content concerns, raw material price volatility, and regional taste preferences.
The Opportunities include global Asian cuisine adoption, low-sodium variants, premium fermented sauces, and foodservice expansion will offer significant growth opportunities in the Soy Sauce market.
Naturally brewed and low-sodium variants; premium and regional flavor profiles; clean-label fermentation techniques are the emerging trends and innovations impacting the Soy Sauce market.
The global Soy Sauce market is expected to be led by APAC during the forecast period.
Some of the prominent players operating in the global Soy Sauce market are; Yamasa Corp., Okonomi, Lee Kum Kee, Masan Group, Kikkoman Corp., Haitian, Otafuku Sauce, Bourbon Barrel Foods, Maggi, and Meiweixian and others.
The report explores crucial aspects of the Soy Sauce market, including a detailed discussion of existing growth factors and restraints, while also browsing future growth opportunities and challenges that impact the market.
HappyClients